
Author: Aadarsh Patel | EQMint
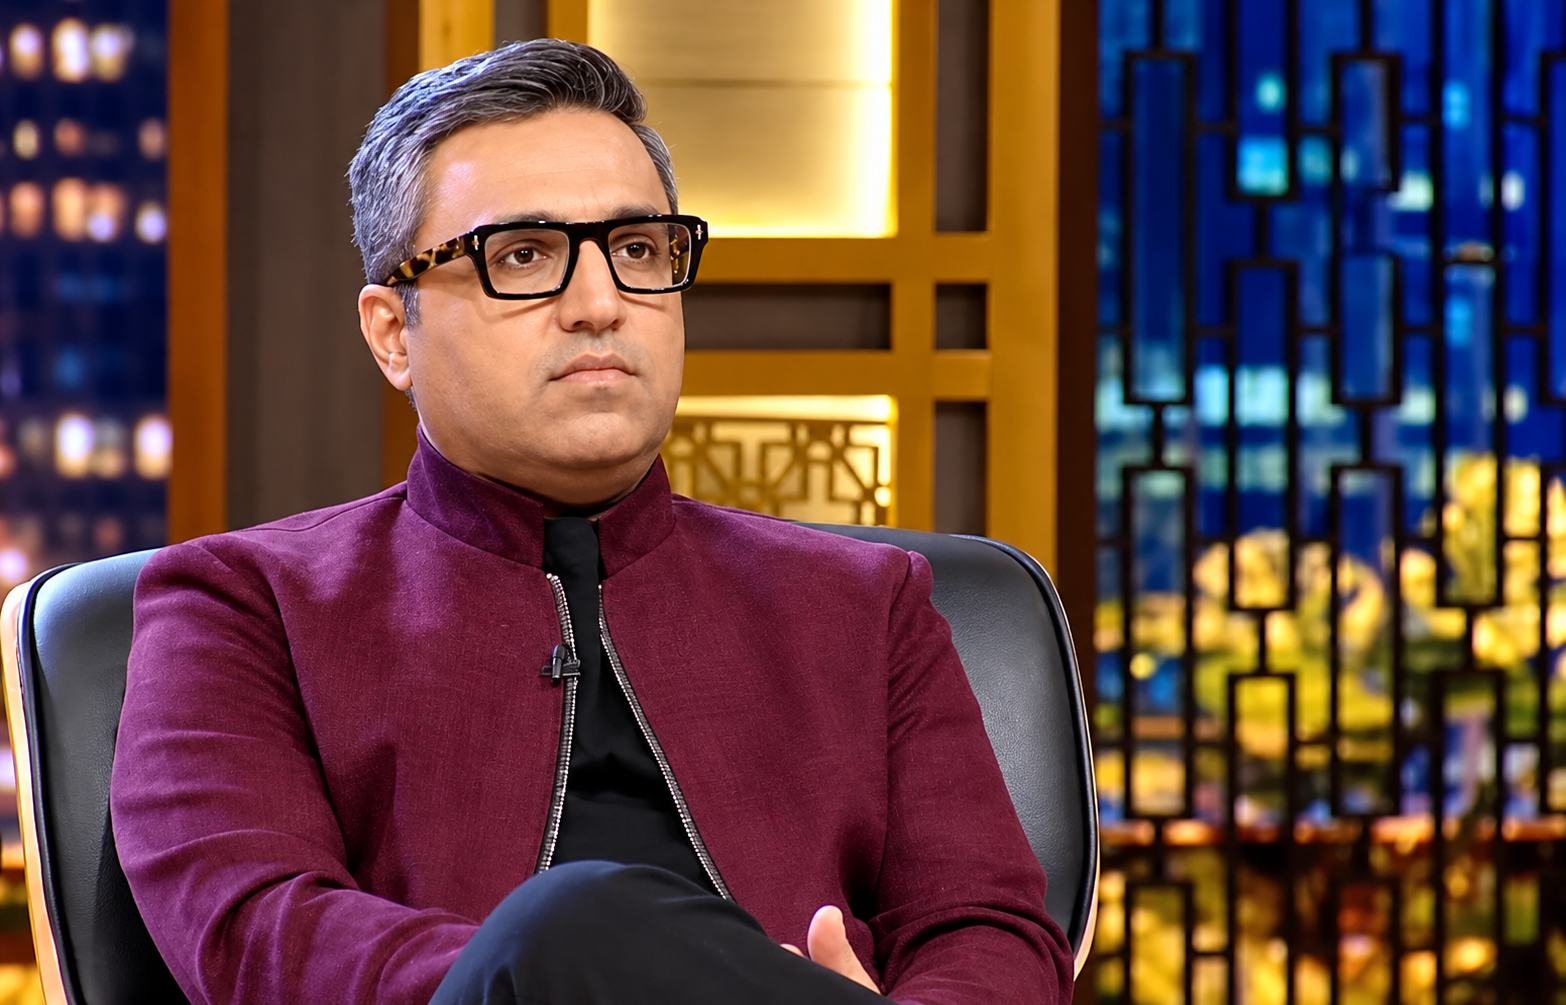
BharatPe co-founder Ashneer Grover has criticised the possibility of charges being imposed on higher-value UPI transactions, calling any levy on the digital payments system “just tax collection” and questioning why UPI needs to be monetised when banks and the broader payments ecosystem remain financially strong.
Grover’s comments came after the government notified that banks and payment system providers cannot impose direct or indirect charges on UPI transactions of up to ₹2,000. The same protection has been extended to RuPay debit card payments.
Ashneer Grover questions the need for UPI charges
In a post on X, Grover questioned what subsidy the government is providing to UPI that would need to be recovered through a transaction charge.
He pointed to several financial figures, including the Reserve Bank of India’s ₹2.87 lakh crore surplus transfer to the government, ₹4.11 lakh crore in total profits reported by listed banks and NPCI’s ₹1,888 crore pre-tax surplus.
Grover also highlighted the estimated ₹30,500 crore annual cost of running ATMs and cash logistics in India. He argued that if the objective is to reduce payment infrastructure costs, promoting UPI instead of maintaining an expensive cash network could be considered.
What the ₹2,000 UPI rule actually means
The government’s September 14 notification does not introduce an automatic charge on every UPI payment above ₹2,000.
Instead, it guarantees that payments of up to ₹2,000 through UPI cannot be subjected to charges by banks or payment system providers. The move follows Parliament’s amendment to the Payment and Settlement Systems Act, 2007, which created a legal framework for allowing charges on certain digital payment transactions.
The ₹2,000 threshold is therefore a no-charge protection threshold, not a UPI spending limit.
Higher-value merchant payments could potentially come under a future Merchant Discount Rate (MDR) framework. MDR is generally a fee paid by merchants for accepting digital payments. However, the rate, eligible transactions and implementation details have not been fully finalised.
Will customers have to pay for UPI?
For now, no.
Consumers continue to be able to make UPI payments without paying a transaction fee, including person-to-person transfers. A payment of ₹2,500 or ₹5,000 does not automatically result in a fee being deducted from the customer’s account.
The current debate is primarily about whether certain higher-value merchant transactions could attract MDR in the future and how that cost would be distributed across merchants, banks, payment apps and other participants.
The government has also maintained that consumers will not be charged for using UPI, while operational details around any future MDR structure are expected to come through NPCI.
UPI’s rapid growth
Since its launch in 2016, UPI has become one of India’s most widely used digital payment systems. According to Economic Times, the value of UPI transactions rose from ₹0.07 lakh crore in FY17 to around ₹314 lakh crore in FY26. UPI is also now accepted in multiple countries outside India.
Grover’s comments have added another layer to the ongoing debate over how India’s rapidly expanding digital payment infrastructure should be funded, particularly as policymakers consider introducing a merchant-side charging framework for some higher-value transactions.
For more such information, visit EQMint
Join our WhatsApp channel for timely updates: Whatsapp