
Author: Nishtha Mehrotra | EQMint
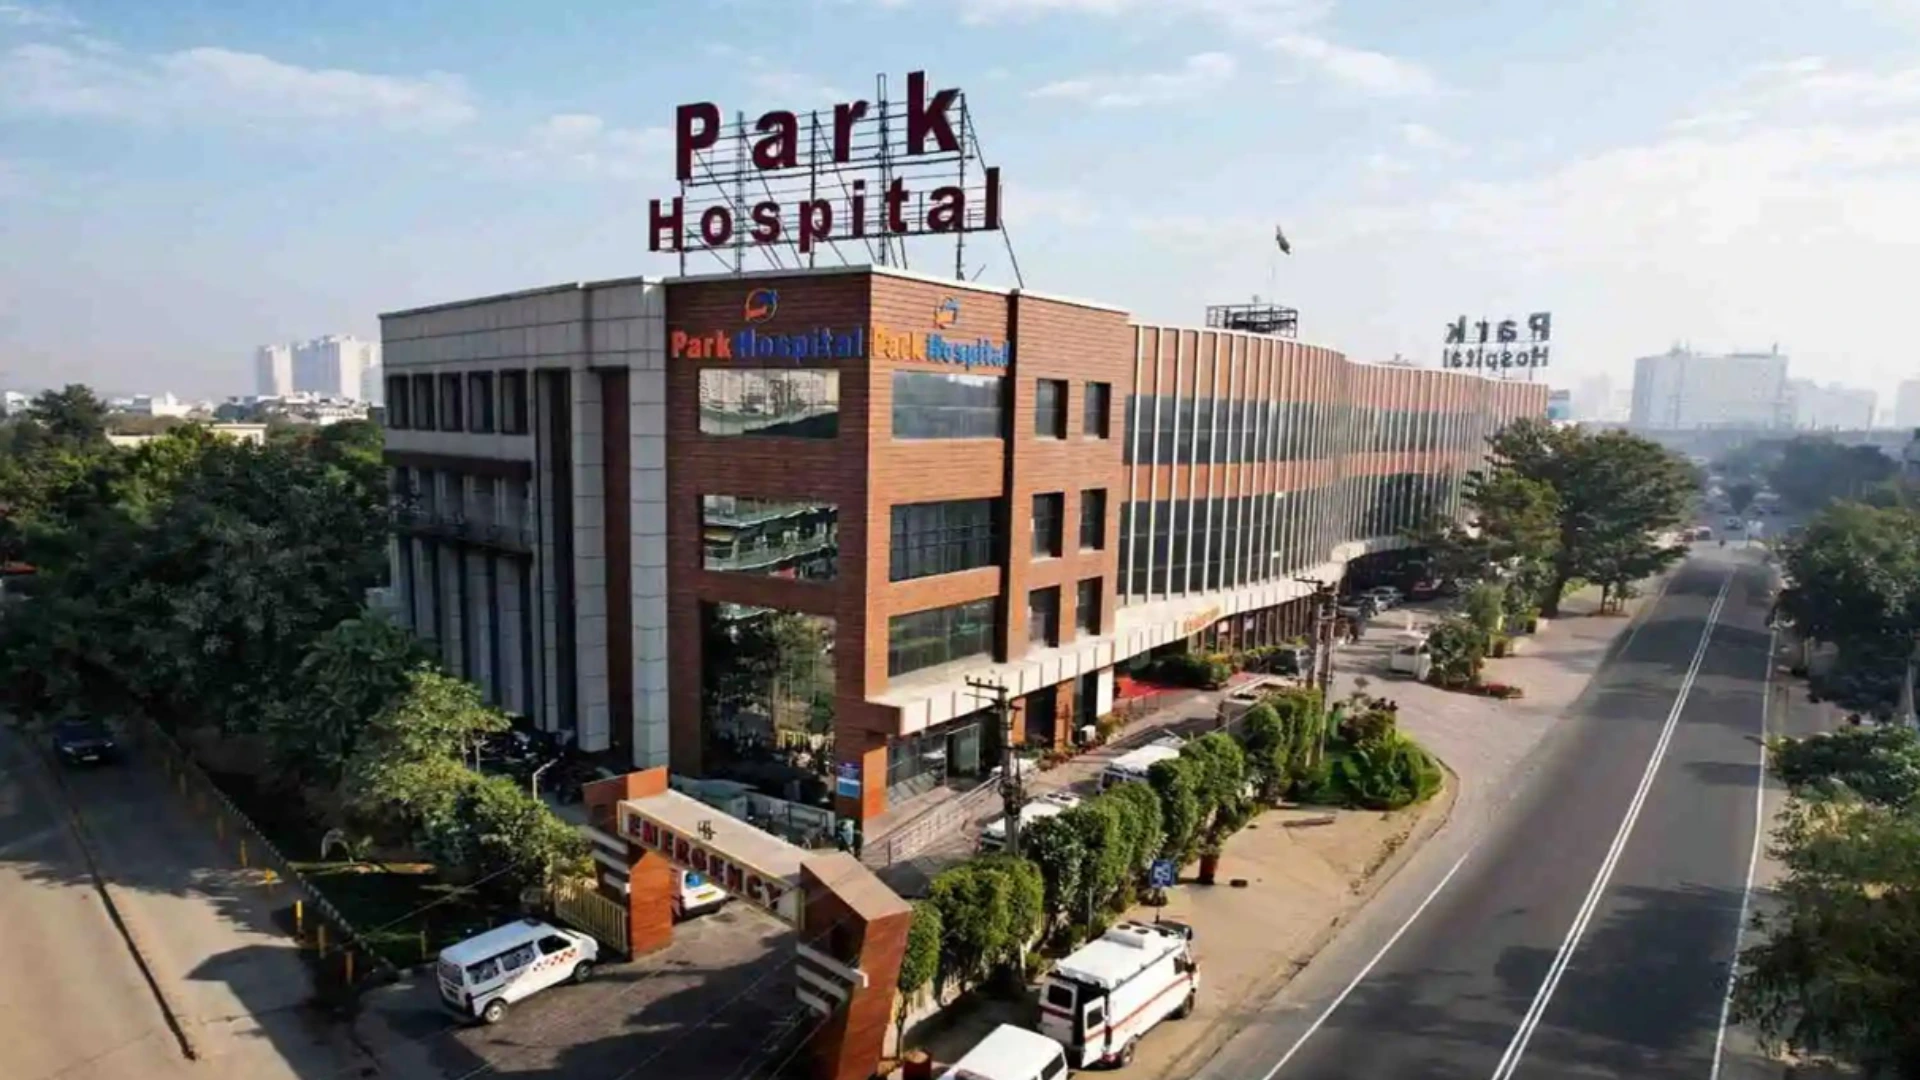
Park Medi World Ltd. (NSE: PARKHOSPS) has sought to reassure investors that a potential cap on cancer drug prices is unlikely to materially affect its financial performance, even as hospital stocks came under pressure following a Supreme Court hearing on oncology drug pricing.
On September 30, the Supreme Court questioned why the existing 16% trade-margin cap applicable to scheduled drugs should not also extend to non-scheduled medicines, including several cancer and chemotherapy drugs. The development triggered a sell-off across hospital stocks, with the BSE Hospitals Index falling around 5%.
Park Medi World, however, says oncology drugs account for less than 2% of its revenue. The company also has significant exposure to government insurers, where medicines are either supplied directly or included in fixed package rates. Government insurers also mandate discounts on high-priced cancer drugs, which Park says are already reflected in its reported numbers.
The company’s low-cost, high-volume model further reduces its dependence on drug margins. In Q1 FY27, revenue rose 19% year-on-year to ₹475.7 crore, while EBITDA increased 20% to ₹126.1 crore, with an EBITDA margin of 26.5%.
Park currently operates around 3,960 beds across North India and plans to add more than 2,100 beds by FY28, with a longer-term target of crossing 10,000 beds by FY33.
Brokerages remain positive on the stock. Emkay has maintained a BUY rating with a ₹375 target, while Choice Institutional Equities has a BUY rating with a ₹350 target.
Disclaimer: This article is for information purposes only and is not investment advice.
For more such information, visit EQMint
Join our WhatsApp channel for timely updates: Whatsapp